Insurance and liability at a public charging site
A public DC fast site is an unusual risk to underwrite because it is three property types stacked on one parcel: a retail pad that strangers drive onto at all hours, a small electrical substation running at a few hundred kilowatts, and a piece of unattended equipment that a driver who has never seen it before is expected to operate correctly. Most commercial insurance was not written with that combination in mind, and the gap between what a standard policy assumes and what a charging site actually is tends to surface only after something has already gone wrong.
What is actually exposed
Strip the site down to its physical risks and four categories cover most of what can happen. Bodily injury from a cable, a connector, or a curb or bollard a driver did not see while reversing toward a stall. Vehicle damage, paint, a bumper, a door, from contact with charging equipment or from a dispenser malfunction mid-session. Property and equipment damage to the dispensers themselves, from a vehicle strike, a vandalism event, or a fault in the switchgear feeding them. And business interruption, the exposure that is easiest to underweight, the revenue a site does not earn while a damaged stall sits dark waiting on a part or a utility reconnection. Host-owned sites carry all four as the landowner's direct exposure; hosted sites shift most of them to the network, but rarely all of them, and rarely without conditions attached.
Where a standard policy stops covering the site
A typical commercial general liability policy is written around the assumption that the insured controls the equipment on its premises and that the equipment does not itself energize at a few hundred kilowatts. Charging hardware breaks both assumptions at once. The dispenser is frequently owned, operated and maintained by a party other than the landowner, which raises a straightforward question any adjuster will ask first: whose policy was in force, and covering what, at the moment of the incident. A landowner's premises policy is not automatically written to extend to equipment it does not own and did not install, and a network's equipment policy is not automatically written to cover a slip-and-fall that has nothing to do with the charger itself. Without a lease or hosting agreement that draws that line explicitly, the two policies can both assume the other one answers the claim, which is the scenario every insurance broker is paid to prevent before it happens rather than litigate after.
The contract is where the boundary gets drawn
Liability allocation at a charging site is set well before any incident, in the ground lease or hosting agreement, and the terms worth checking for are specific rather than general. An additional-insured endorsement naming the landowner on the operator's liability policy, not just a reference to "adequate insurance" in the body text. A waiver of subrogation, so the operator's insurer cannot turn around and sue the landowner to recover a payout on an incident the lease already allocated to the operator. Indemnification language that names equipment damage, bodily injury and business interruption separately, because a single blended indemnity clause tends to leave exactly the gap described above. And minimum coverage limits sized to a public, high-traffic, high-voltage site, not copied from a generic retail pad template that predates the charging use. None of this is exotic insurance; it is ordinary commercial coverage, written and allocated with the actual equipment and actual traffic pattern in mind.
What a host-owner should ask for before signing anything
An owner developing a site directly, rather than leasing the parcel to a network, inherits the full exposure and should underwrite the coverage with the same rigor as the electrical build. Equipment manufacturers typically carry product liability for defects in the hardware itself, and a host-owner should confirm that coverage exists and ask for the certificate rather than take the sales conversation's word for it. The installer or EPC contractor should carry its own liability through a commissioning period that extends past the ribbon-cutting, since installation defects tend to show up under load, not on day one. And an umbrella policy sized to a public-facing, unattended, high-voltage asset, not to the general commercial limits a landowner already carries for the rest of the parcel, closes the gap a single large claim could otherwise open past any one policy's limit.
None of this is a reason to avoid host ownership. It is a reason to treat the insurance review as part of the underwriting, not an afterthought handled by whichever broker already covers the rest of the property. A site that has priced its coverage correctly from the start is a site whose economics do not change the first time something goes wrong.
Model the site before you insure it
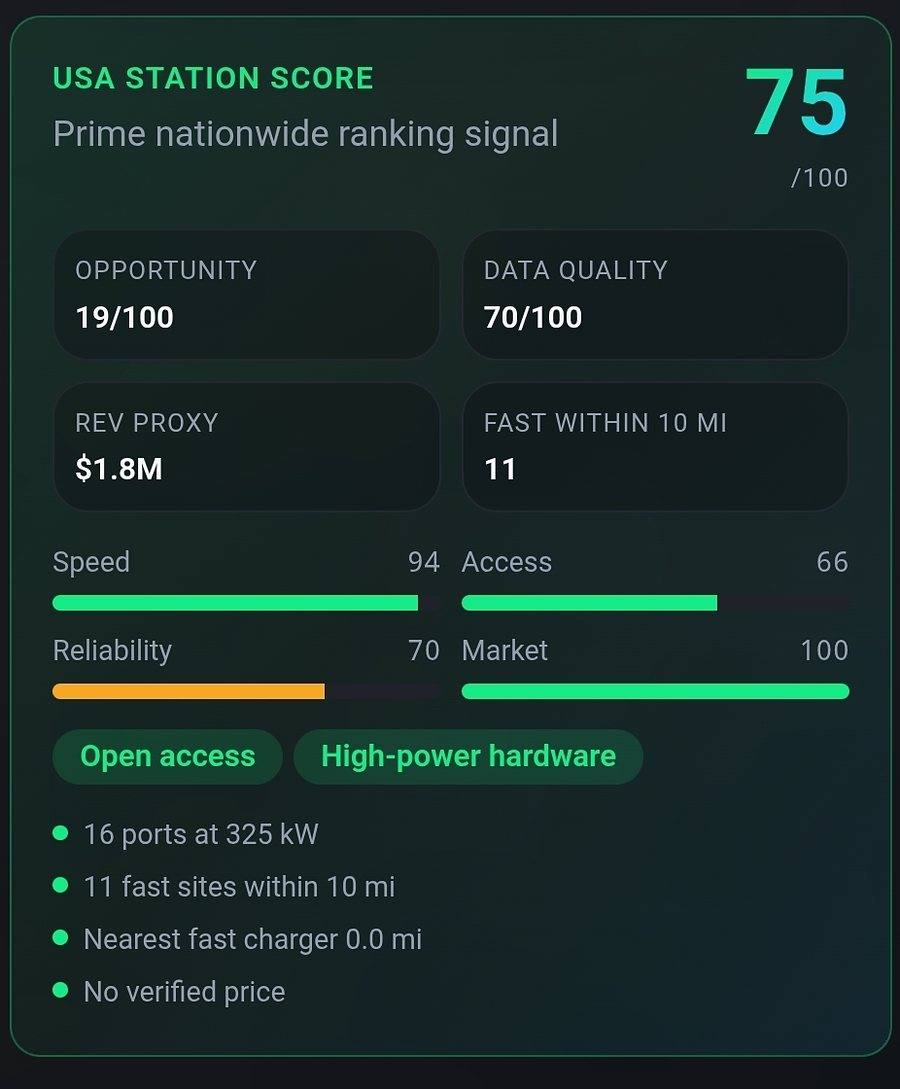
Enter an address and our site-intelligence layer returns the parcel, utility territory and reliability signals worth bringing to the insurance conversation, before coverage gets priced off a generic template.
Run a Site Scan